

Welcome back to Late Filing. I hope you’ve had a fabulous week!
Every quarter or so, I do a big Q&A with an expert – a divorce lawyer, a personal trainer, a nutritionist. For a while now, I’ve wanted to talk to a money guru, but I just couldn’t find The One. As you are probably aware if you’re a regular reader of Late Filing, I really like nice things. (I imagine you do too if you were inclined to hit ‘Subscribe’.) Most of the personal finance experts I come across, ostensibly, do not. Saving is good. Investing is great. But I also want to wear beautiful clothes and go out to eat and enjoy my life. Ergo, I am not inclined to take advice from anyone who’s living in a sensory deprivation tank just so they can retire at 40.
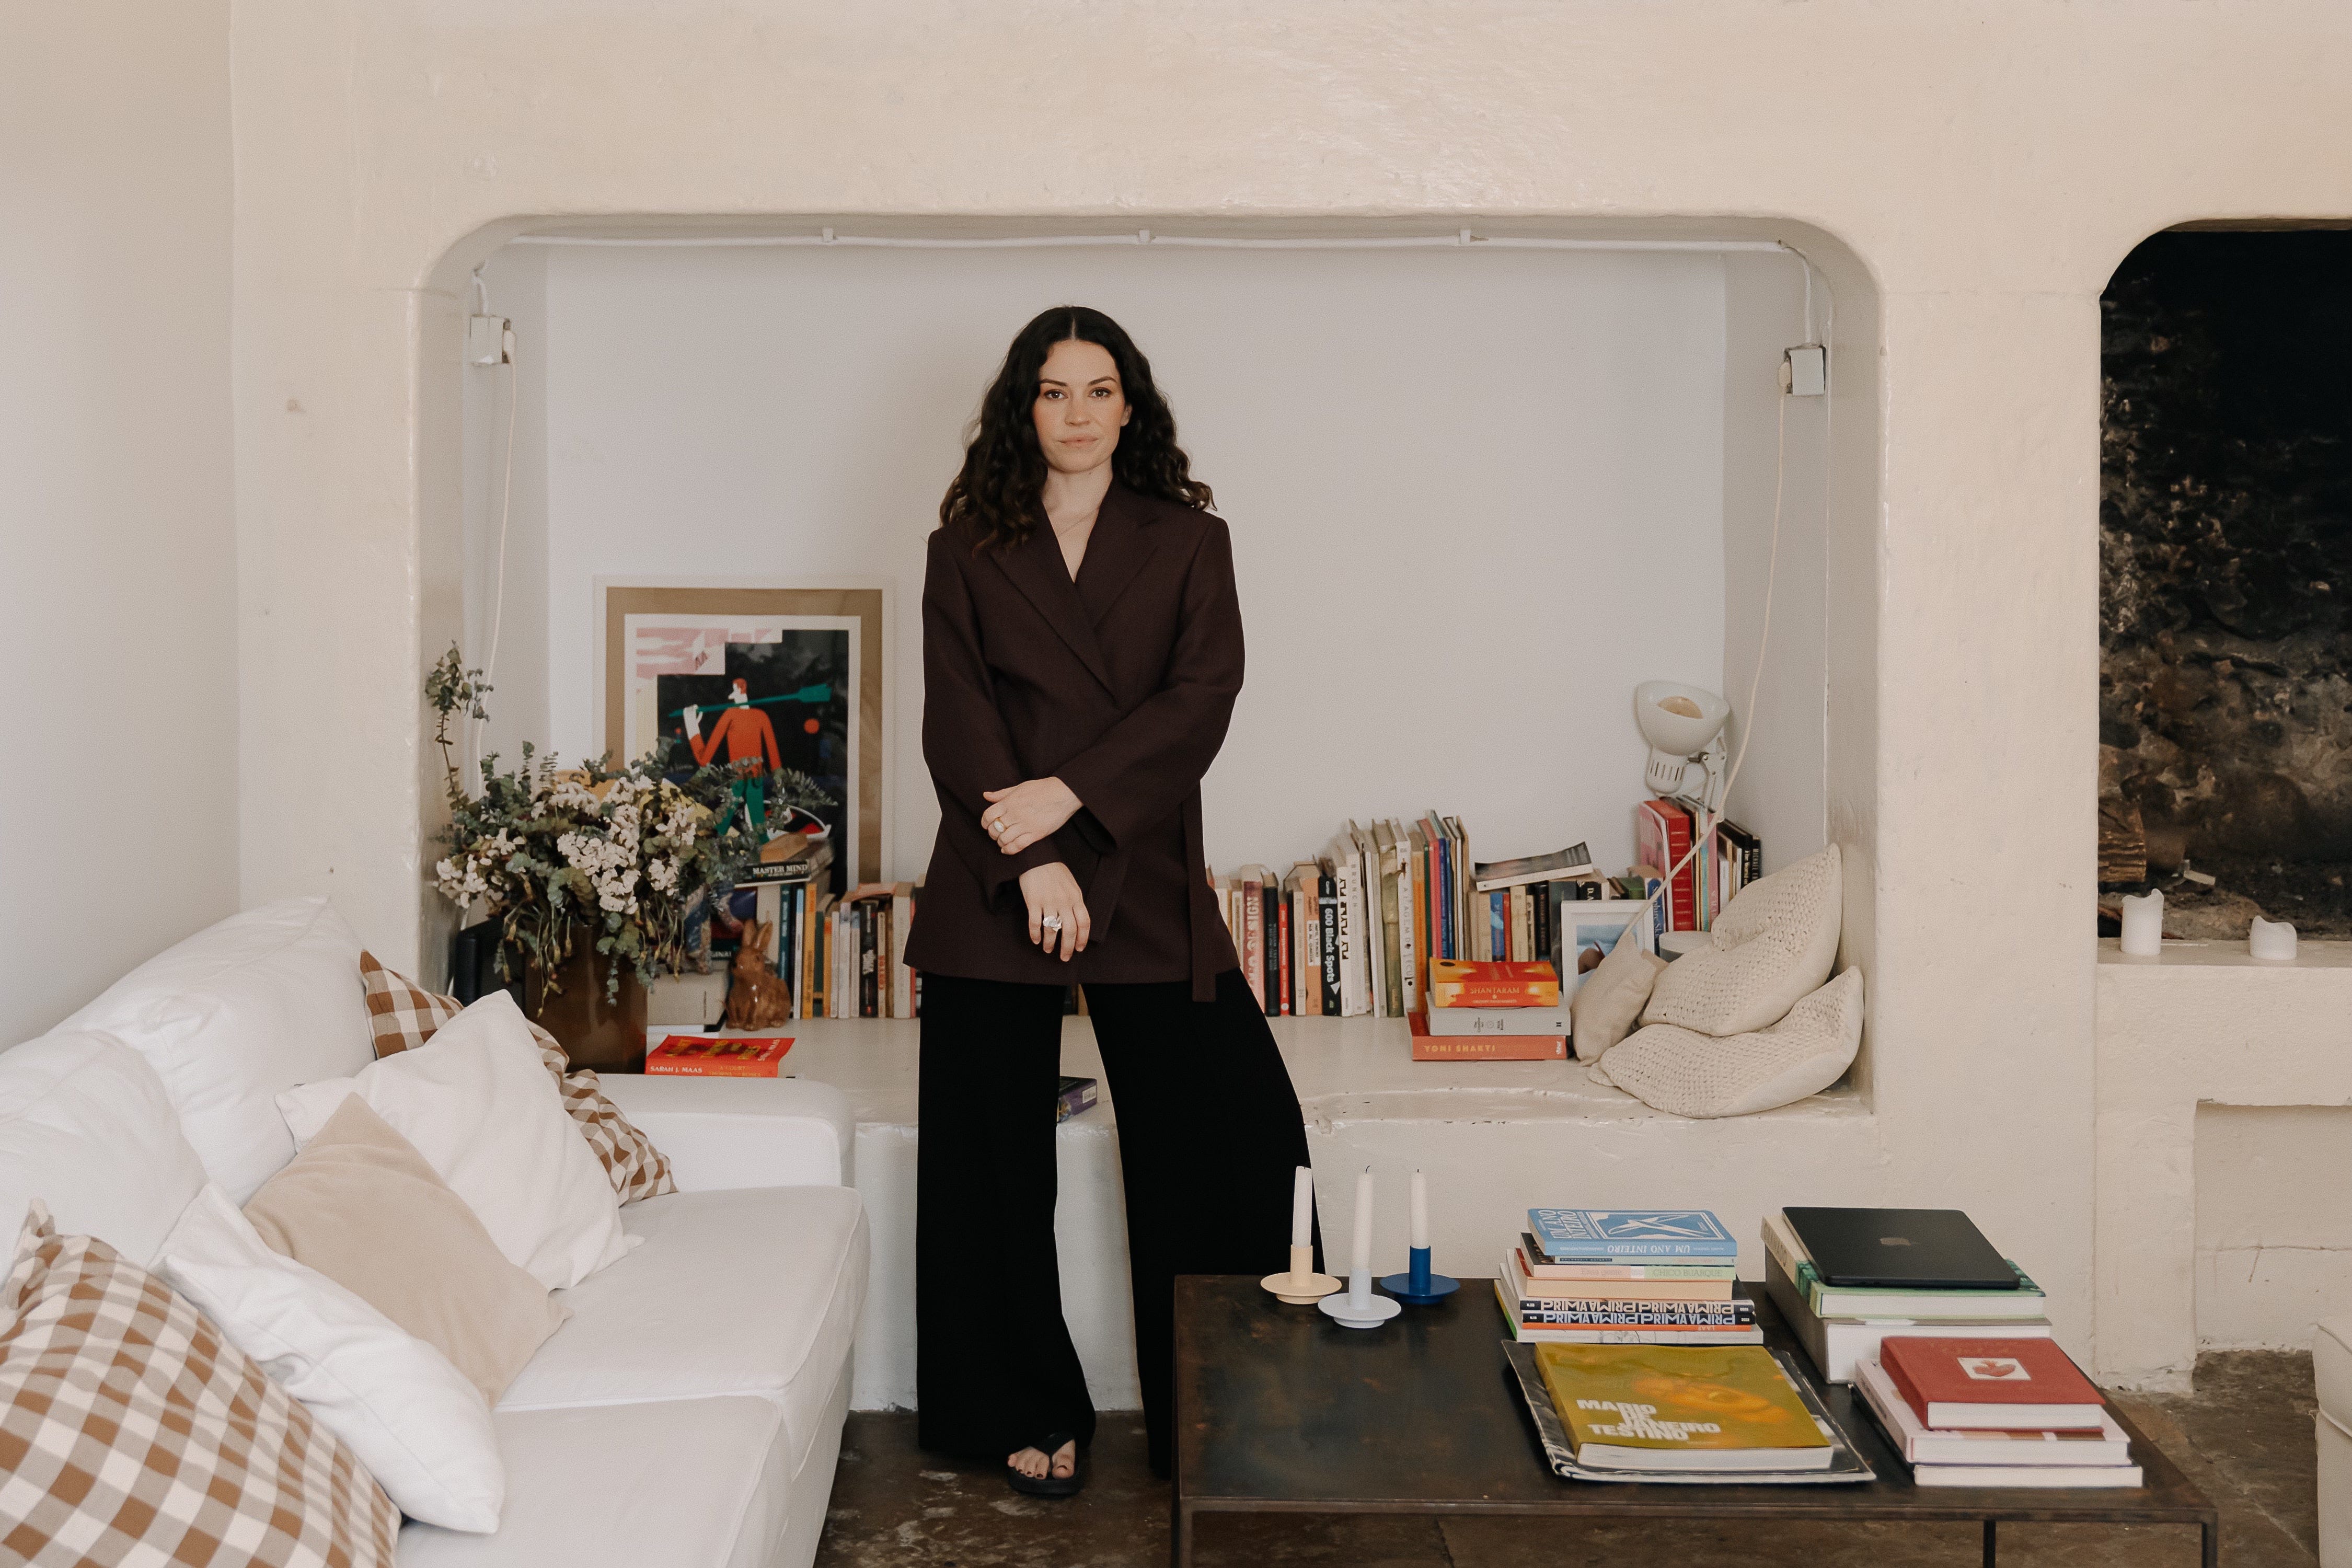
When I came across Hannah Mayfield, who runs What Is Wealth, I knew she was my person. First of all, she is accredited, which I felt was important. But beyond that, Hannah has style! She used to work in fashion before training as a financial adviser. She’s into interiors! And after I watched a bunch of her videos, it was clear to me that her philosophy wasn’t one of short-term misery. I absolutely loved chatting to her, and I felt excited about applying some of her wisdom rather than guilty for having expensive taste in skincare.
A note to non-UK readers (of which I know there are many) that some of the things we got into are UK-specific: Plan 2 student loans, ISAs, what happens when you earn over £100k. However, a lot of Hannah’s advice – about investing, earning potential, what to do with a lump sum – is pretty universal. And if you are a finance whizz who works in The City, then you likely already know a lot of this stuff, but I wanted it to be as accessible as possible and really cover the foundations.
Also, I deliberately don’t paywall these expert Q&As so as many of you can read them as possible. But if by the end of this interview, you think, ‘Hey, I really got something out of that’, then consider upgrading to a paid subscription, which gets you access to more Late Filing and allows me to deliver bigger, better stories to you. It’s just £5 a month, which I truly believe is insane bang for your buck. Better yet, if you’re in savings mode, there’s 10% off annual subscriptions (which works out at £3.75 a month) until next week Saturday.
Fedora: I’d love to know a bit more about your own journey into becoming a financial adviser.
Hannah: It was very much through circumstance. I started my career in fashion buying and then when I was 22, my dad died and I received a chunk of money because he hadn’t made it to retirement. I’d grown up with a single mum in a low-income household. I was good at budgeting, but in terms of actually having money and how to grow it, I’d never had any education around that. I taught myself what to do with money and how to invest, and it was just a personal thing, but over time my investments grew and I got more confident with it. In 2020, I started teaching my friends over Zoom how to set up an investment portfolio and theirs started growing too. I realised there were so many other people out there who could be doing this but the information’s not out there, so that’s when I started speaking about money online.
When I got my financial adviser qualification, I knew I didn’t want to go down the traditional financial advice path because it only really helps a small percentage of people. I took it down the financial education route instead where I’m sharing best practice: this is how to think about money, this is how different assets work. I do work with clients, mainly women, teaching them all this stuff, but then also there’s this whole creator industry that I’ve ended up in as well.
What would you say was the most important thing you learned in your financial education?
I’d say there were two things. There was that practical side: how the stock market works and that it isn’t just gambling. And then there was the emotional side, which is that you have a relationship with money and it’s probably based on weird stuff from when you were growing up. I had to really interrogate: what have I been taught about money and what do I want my financial life to be like as an adult?
Obviously a big part of how much money you have is how much you make. I read this quote about how you can’t fight the market – if you work in an industry that is struggling, it doesn’t matter how brilliant you are, there’s a real cap on your earnings. Do you think knowing what you know now you’d have picked fashion buying in your twenties?
Knowing what I know now, probably not. Because it isn’t the most well-paid career. At the time I was very much like, ‘I don’t care about earning loads of money – I just want to do something I love.’ And actually, I think it’s helpful to be a bit pragmatic because life is quite expensive. And why can’t you get both as well? Something that is highly paid and that you really enjoy. People can make good money in fashion, but it’s a bit of a grind and especially at the start, it’s not well paid. I would probably go back and be like, tech! The internet! This is what’s growing, and that’s probably good to get in on.
Do you ever give clients advice on boosting their earnings?
I always say your earning potential is your biggest asset. I’m always in favour of earning more. I share an office with my friends and our WhatsApp group is called The Money Makers and we all hype each other up to earn more and pitch more and negotiate. My audience is a lot of women, and I just don’t think we’re culturally socialised to think like that as much. I think in your career, it’s about preparing for your negotiations, practising the number, making sure you know the market rate. Think about what you’re adding to the business and approach your salary in that way. Keep a record of everything and go in prepared and ask for it. Because if you don’t ask, you don’t get.
‘When I’ve explained investing to my clients, they’re like: “Is that all I have to do? Surely it’s not that simple?”’
Do you abide by the 50-30-20 rule with take-home earnings? (As in 50% to necessities, 30% to non-essentials and 20% to savings, investments etc.) Or would you say it’s case by case?
I always think with money, there are so many factors to consider, and the 50-30-20 rule is useful to give someone an idea. But with the 50%, for example, a lot of it is going to be housing costs and that depends on where you live. I think it’s a good framework to have, especially if you’re looking at whether you can afford to move somewhere more expensive. Maybe those costs would be 60% of your take-home pay and perhaps that’s a bit unaffordable. Or maybe it’s ‘I should try to earn a bit more so that I can put aside that 20% for my future self.’ But I’m not into strict frameworks. I think the main thing to take away from it is the percentage that you’re putting towards your future.
I think about wealth as these three levers that you get to pull. First is your income. How much am I going to earn over my lifetime? What am I doing about that? The next lever is how much of what I’m actually getting am I retaining and putting towards the future? Is that 20% of my take-home pay? Is it 10%? And obviously the more you can pull that up to have that higher savings rate percentage, the more you’ll have for your future. And then the third one is the rate of return, or how much your money’s making for you. There are a lot of people who are good at saving and have stashed up all this cash, and they’re not doing anything with it. It’s making them 3 or 4% when it could be making a lot more.
What sort of challenges do you find that your clients come to you with consistently?
I work a lot on the investing side, and I think the real challenge is people just don’t understand it. It’s in the zeitgeist enough that they get that it’s something that they should be doing, but they find it overwhelming. And then what happens when I’ve explained it to them is they’re like: ‘Is that all I have to do? Surely it’s not that simple?’ I’m personally a passive investor – I invest in index funds. And when you understand it, it’s like: ‘Oh, that’s it?’ You just have to put it in there and just keep it growing for years.
Do you have a particular strategy when getting into investing? I was definitely late to setting up an account on Vanguard and getting into index funds.
I’d say the main thing, if people are kind of starting from beginner, is to learn about index investing. You want the investments you choose to have low fees, because a 1% fee really adds up over time. And you want it to be diversified, which means you want to spread your money out a lot. Index investing is a really great way for those two things to happen. You own little bits of these companies and then you get a little bit of their profits. These funds are basically just bundling loads of companies together for you, so instead of having to go out and pick every single one, you can just buy one fund. It’s less risky because if some companies don’t perform well, you still own plenty of others. It’s just the best starting point.
What’s your approach to student loans – specifically the Plan 2 loan? Is it worth paying it off in one go if you can?
So, for anyone who went to university from 2012, only one in three people are ever going to pay that off, so you can kind of think of it as a graduate tax. If you’re a higher earner and you’re definitely going to pay it off, then of course, if you paid it off sooner, you wouldn’t have to pay all that interest. But equally, if there are other things your money needs to go towards, like a house or a pension, it’s better to put it towards that rather than paying off your student loan in one go and you just kind of have to accept that it’s going to come out of your bank account every month.
What would you classify as a high earner? I think in one of your videos you made you said £50k, which really surprised me.
So, I’d say if you’re on £50k and you’re on track to be on around £100k as you get further into your career, then you would probably be someone who is more likely to be that one in three.
Is there anything you’ve changed with your spending since you’ve become more financially literate? I feel like part of what puts me off so much personal finance content is that it’s all just: ‘This is a waste of money! You don’t need this!’ Their houses have bare walls and sad furniture. I don’t want to live like that. I’d love to know what your approach is.
Growing up, I was a very restrictive spender. It was always ‘I can’t have that’ by default. I sometimes say there are two types of spenders: default yes and default no. Default yes people are like ‘I want to get it’ and have to talk themselves out of it, whereas default no people are like ‘I can’t have anything’ and have to talk themselves into it. I was always very considered with my spending but at the same time I’ve always liked nice things and would save up for them. I love interiors, for example, and I have all these Pinterest boards.
If you’re like that, then you just have to be a bit more strategic on what you’re spending in terms of maybe sourcing it and taking a bit longer to find the right thing. Figure out what you care about, so you can say in advance: ‘It’s fine for me to spend that.’ And then with other things, it might be: ‘I overspend on this and it isn’t ideal.’ If you can do it, then do it, but if it’s compromising your future and you want to have more in savings and investments, then you probably need to add in some filters.
I feel like what you decide is worth spending your money on is so personal. I’d love to know what ‘luxury’ is worth it to you and what you’d say is a waste? I’ve definitely wasted money on Deliveroo.
For me, it’s anything that’s for your health and wellbeing. I have a really nice gym I go to and it actually makes me want to go a lot and I think that’s so worth it. One of the best things I’ve ever spent money on is therapy – if you’re having any kind of issues and you can afford therapy, you should go. What’s not worth it? Yeah, it probably is stuff like food delivery. They’re good for convenience, but there’s also the hedonic adaptation thing where you just get used to a certain standard and then it’s not even a treat anymore.
And then when it comes to savings, what’s your approach to that? Sometimes it can get tempting to move a chunk of savings to investments when you see how much more they’re growing.
I’d say the first thing is pay off any expensive debt, like credit cards or loans that have high interest rates because they’re just going to be dragging you down. Then you move on to savings. So, do I have three to six months of living expenses in a separate savings account? That’s a kind of standard goal, because if you lose your job, you have a three-to-six-month window to get a new one and you can get yourself into a really good position. I think a lot of personal finance is making sure you’re not backed into a corner.
Then other than that, save towards any big things that are coming up in the next year – like if you’ve got a holiday coming up. And then is there anything big happening in the next five years? Say, if you want a house deposit or a wedding or to cover maternity leave or a kitchen renovation or whatever. I would probably keep that in cash. And then anything I think is for the future – five years plus is the rule of thumb – I’d invest.
‘Try to be a bit neutral and pragmatic about debt. “This is a number. I want to get it paid off. What can I do?”’
Do you have any savings accounts that you particularly like? I moved some of my savings to Monzo a while ago because I noticed their interest rate was a bit higher, for example.
It always changes. I think if you have a big chunk of cash, always look for the best interest rates. Otherwise, I am just a fan of whatever’s simplest. Maybe you need to have it in a savings account where you can’t just keep transferring it back and forth. But in general – not specifically for saving – I do like the current accounts that have really good functionality. Revolut and Monzo have all those good budgeting tools in them and the pots features and the roundup features. They also categorise your spending for you, so you can see how much you spent on food shopping or eating out and whether it’s more than you thought.
How do you feel about credit cards? And what would be your advice to anyone who’s accrued credit card debt and wants to pay it off and boost their credit score?
I think the first thing is actually looking at your credit score because it’s really important. One thing people don’t know about as much is that being registered to vote at your address boosts your credit score. Also when you get a joint account with someone, you become financially linked in the eyes of credit providers, so before you go into that, you need to have open financial conversations.
With credit cards, it’s about knowing yourself. If you’re someone who can get into the habit of whacking it on a credit card really quickly, maybe it’s not the best thing for you. They can give you a bit of extra protection, say if you book a holiday on them, and some people like them for points. I’m personally an advocate of having the simplest financial setup – I don’t want to have little random amounts I have to pay off and not have good oversight, so I don’t really spend on a credit card because I just find it annoying. I just have one for car hire and stuff like that.
If you’re someone who has accrued credit card debt, it’s about having a plan and writing them all out. What’s the card? How much have I got to pay off on it? What’s the interest rate? There’s the snowball method, which is paying the smallest one off first, just so you get that satisfaction and motivation from being able to close it down. Or there’s the avalanche method where you pay off the minimum on all of them and then can overallocate on the one with the highest interest rate.
I think it’s about just trying to be quite matter-of-fact about it as well. Money can feel super emotional and sometimes we avoid it because we’re avoiding these horrible feelings of shame and guilt. Try to be a bit neutral and pragmatic about it: ‘This is a number. I’m paying a lot in interest. It’s just not helpful and I want to get it paid off. What can I do?’
What do you think are the financial conversations you need to be having before you embark on a relationship, move in with someone or get married?
It will probably happen differently for everyone. I think you should know whether you have the same vision for your future together. Do you care about the same things, like living in a certain area? It’s important to have a picture of what your life together is going to look like because money affects that. I think before opening a joint account, it’s good to have a conversation of how it’s going to work. Are we both going to put in all our money? Are we going to do 50/50? Are we going to do it proportional to salary? I don’t think there’s necessarily a right way of doing it – I think the right way of doing it is the one that you’ve spoken about together and feel comfortable with and which feels fair. What I do have very strong opinions about is when people, especially women, have children. The ‘motherhood penalty’ is when everything gets super inequitable.
In what way?
I’m going to be a bit gender specific, but typically the mother is the caregiver, and they maybe take time off work or they’ll take a bit of a backseat in their career or they’ll go part-time. And if you’re out of a workforce for a few years, you don’t get any pension contributions, so there’s this problem later down the line where whoever’s going to work, they’re getting all their pension contributions and promotions and their earning potential as an asset is increasing. And for the person who’s the caregiver, it just becomes really hard to catch up. Because of the way these kind of investments work, a small amount of money now is so much more powerful than the same amount of money ten years later. I think that’s when you have to have conversations like: ‘Okay, if I’m taking a step back from my career, I’m going to be financially penalised in all these ways, and how are we going to navigate that as a team?’
What would your advice be to self-employed people about managing their money – particularly things like savings and pensions?
One thing a lot of self-employed people don’t think about is insurance, so I’d say look into things like income protection insurance. What would happen if you couldn’t work? If you get sick, it will cover some of your income. And then with your pension payment, what I would say is you probably need to be putting a lot more into it than you think – so run the numbers and figure out how much it should be.
Also, if you’re self-employed, remember that someone hiring you doesn’t have to pay national insurance or sick leave or holiday or make pension contributions. You need to be factoring that in and you might realise that you should be charging a bit more because you need to take on all those costs. It’s good to be aware of that so you can stand behind your rate.
When it comes to buying property, there are obviously so many things to consider: lifetime ISAs, shared ownership, leasehold vs freehold. Is there anything you’d recommend and not recommend?
I think the main thing I’d say about buying a house is that it’s a long-term decision. We’ve had this era of ‘I’ve got to get in there super quick because it’s going to go up in the next few years, then I can sell it for a profit and buy my next house’. Now I think the property market in the UK is a bit more stagnant, and ideally you want to be buying something that you can stay in for a long time. Also stamp duty is expensive and you’re never going to get that back. You might buy somewhere and then realise two years later that you don’t really want to be there anymore. You’ve just lost all that money and then you have to pay it again.
What would you recommend someone do with a lump sum, like inheritance or a book advance or a bonus?
Definitely put it in a different account. With these lump sums, it sounds like a lot but it’s quite easy to spend little bits here and there, and it can really start to dwindle. So try to keep it separate and be really strategic about it: where’s the best place that I could put this money? How can I maybe use it towards my future? Especially if you’ve got your living costs covered and you can just kind of stick with what you’re used to. I had a friend who I was helping a while ago who got a big bonus after her company was bought and she realised she hadn’t been paying enough into her pension over the years and so it all went towards that. Unfortunately, it’s probably about running the boring numbers and thinking: how’s my pension? How are my investments? Should I overpay on a mortgage? Think about the big future things and then maybe you earmark an amount that you’re going to enjoy.
‘A lot of people get into that mindset trap of “I’ll put more into my pension when I make more” but £1 you put in today is worth more than in 10 years’ time.’
Something I’ve written about in The Digest is the ‘£100k tax trap’. What are some things that you think people should know at that income level?
I think the first thing to know is that when you start earning between £100,000 and £125,140, it’s not that you earn less, but on that section of money that you’ll be taxed more. So don’t be afraid to earn over £100k, basically. But you want to look into pensions and salary sacrifice because in that bracket between £100k and £125k, you pay 60p tax for every £1 that you earn. If you put it in salary sacrifice or pension, you won’t feel it in your take-home pay because it will just be going towards the future in a way that’s a bit more tax efficient. And also it’s important for the childcare funded hours because if you earn over £100k, you lose a lot of childcare funding and that can be really expensive, so you need to get your net adjusted income down.
I see a lot of figures about how much money you should have in your pension by the time you’re 30. Do you think there’s a set number?
I don’t know if there’s a set amount, but I’d say the earlier you put money in, the more it will work for you. A lot of people, especially who are self-employed, get into that mindset trap of ‘I’ll put more in when I have more’, but £1 that you put in today is worth more than in 10 years’ time. Be more aggressive about giving it time to grow.
I have pensions all over the place from previous jobs. Do you recommend combining them and if so, how do you decide which one to put them in?
I think if you’re okay with them being separate and feel on top of it, then that’s fine. But there are billions of pounds in unclaimed pensions in the UK, so I’m a bit more in favour of putting them all in one place so you can see how much you’ve got and how much you need to put in. You need to check before you consolidate that you’re not going to get any penalties for moving them over. But in general, I think having oversight of your finances is really valuable. As for the platform, I’d just say go for the one that’s easiest for you – one with an easy-to-use interface where they’re making the process simple.
Finally, I’d love to know if there’s one money myth or piece of financial advice that you wish would go away?
I think for women, sometimes the emphasis on frugality is a bit OTT. It’s definitely easier to save a pound than earn a pound – literally when you consider taxes. But also as women, I think if we had conversations about growing your money, increasing your income, investing, getting your money working harder for you, that would be more powerful.
British people need to appreciate SIPP and ISA tax benefits- better than many countries!
This was such an amazing interview; what brilliant advice from Hannah! And thank you for making it a free read; really fascinating.